Results

The reviews are nice. The numbers are better.

We're sitting on 5.0 from 30 Google reviews, and a good run of them scrolls below. But reviews are opinions, so here are eight real purchases as well, made at different points over the past two years across seven different markets. What the data said before we bought, what we paid, and what's happened since. No smoke. Just the workings.

★★★★★

Tried the DIY research route before finding Dan.

Sam Cooper · Google review
★★★★★

Didn't think a buyer's agent was useful. Then came the conversation with this one.

Luke Lehmann · Google review
★★★★★

Works in the mortgage industry and still chose Dan for their own investment purchase.

Alex Robertson · Google review
★★★★★

Skeptical at first, then found Dan went above and beyond to find the right property.

Scott Mccormack · Google review
★★★★★

Was reluctant to use a buyer's agent until recommendations from friends won them over.

Tim Danaskos · Google review
★★★★★

Found Dan helpful and supportive through their first investment purchase.

Elisha Naish · Google review
★★★★★

Found Dan's communication easy, professional and efficient.

Ali Ahmadi · Google review
★★★★★

Says Dan's commitment to clients is second to none.

James Pitt · Google review
★★★★★

Says Dan did an amazing job securing their first investment property.

Angus Robertson · Google review
★★★★★

Refers clients to Dan without hesitation.

Matthew Tully · Google review
★★★★★

Praised Dan's integrity, care and clear strategy.

Tom · Google review
★★★★★

Says Dan supported them through every stage of the purchase.

Dan Gough · Google review
★★★★★

Calls engaging Dan one of their best decisions. Professional throughout.

Daniel · Google review
★★★★★

Recommends the agency to selling agents with off-market properties.

Brian Mishra · Google review
★★★★★

Excellent to deal with, and will use Dan again.

Michael Kotzur · Google review
★★★★★

Thanked Dan and Kate for the help purchasing their investment property.

Kara Davies · Google review
★★★★★

Thanked Dan for helping secure a heritage home in regional Victoria.

Janine Baker · Google review
★★★★★

Genuine, honest and knowledgeable.

Liberty Meehan · Google review
★★★★★

Dan secured their first investment property and handled all the agent comms.

Daniel Taylor · Google review
★★★★★

Tried the DIY research route before finding Dan.

Sam Cooper · Google review
★★★★★

Didn't think a buyer's agent was useful. Then came the conversation with this one.

Luke Lehmann · Google review
★★★★★

Works in the mortgage industry and still chose Dan for their own investment purchase.

Alex Robertson · Google review
★★★★★

Skeptical at first, then found Dan went above and beyond to find the right property.

Scott Mccormack · Google review
★★★★★

Was reluctant to use a buyer's agent until recommendations from friends won them over.

Tim Danaskos · Google review
★★★★★

Found Dan helpful and supportive through their first investment purchase.

Elisha Naish · Google review
★★★★★

Found Dan's communication easy, professional and efficient.

Ali Ahmadi · Google review
★★★★★

Says Dan's commitment to clients is second to none.

James Pitt · Google review
★★★★★

Says Dan did an amazing job securing their first investment property.

Angus Robertson · Google review
★★★★★

Refers clients to Dan without hesitation.

Matthew Tully · Google review
★★★★★

Praised Dan's integrity, care and clear strategy.

Tom · Google review
★★★★★

Says Dan supported them through every stage of the purchase.

Dan Gough · Google review
★★★★★

Calls engaging Dan one of their best decisions. Professional throughout.

Daniel · Google review
★★★★★

Recommends the agency to selling agents with off-market properties.

Brian Mishra · Google review
★★★★★

Excellent to deal with, and will use Dan again.

Michael Kotzur · Google review
★★★★★

Thanked Dan and Kate for the help purchasing their investment property.

Kara Davies · Google review
★★★★★

Thanked Dan for helping secure a heritage home in regional Victoria.

Janine Baker · Google review
★★★★★

Genuine, honest and knowledgeable.

Liberty Meehan · Google review
★★★★★

Dan secured their first investment property and handled all the agent comms.

Daniel Taylor · Google review
Bought July 2025

Victoria

What we saw: 0.41 months of inventory. There was effectively nothing for sale. Homes were moving in 21 days. And rents had been compounding at 7.8% a year for five years while prices had only managed 3.9%. Rent running ahead of price is the setup we look for.

The buy: $807,000 for a house on a subdividable block, which was the whole brief. The clients run an electrical business, and this was their second purchase with me inside a couple of months.

$807,000
Purchase price
$920,000
Valued 12 months later
+$113,000
Growth
21 → 10
Days on market

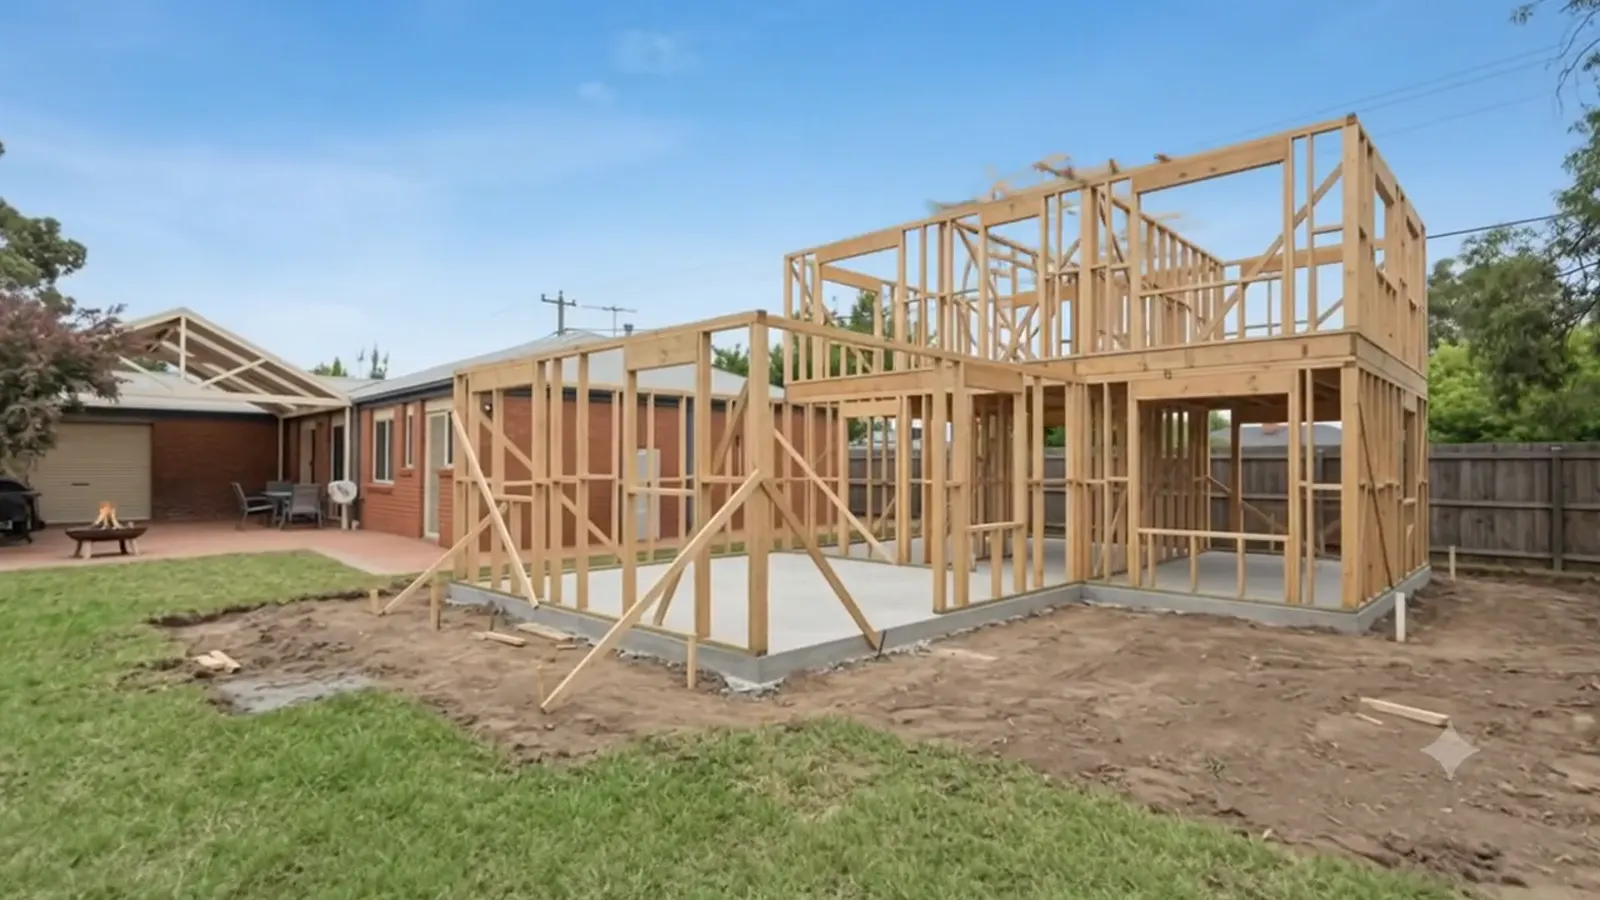
What happened: valued at $920,000 twelve months later, up $113,000, or 14%. They're now subdividing and building a second dwelling out the back, which turns one good buy into two incomes on the same land. The suburb has done its bit too: days on market has halved to 10 and rents are still compounding at 8.6% a year.

Stress tested before we bought: at 2% higher rates, interest on an 80% loan here is $248 a week more. The purchase had to hold at that number first. Every one of ours does.

Bought early 2026

Victoria

What we saw: 0.85 months of inventory in an established middle ring suburb, vacancy at 1.51%, and a five year price growth rate of just 3.93% against rent growth of 5.34%. A suburb that had been sitting still while the fundamentals underneath it kept tightening.

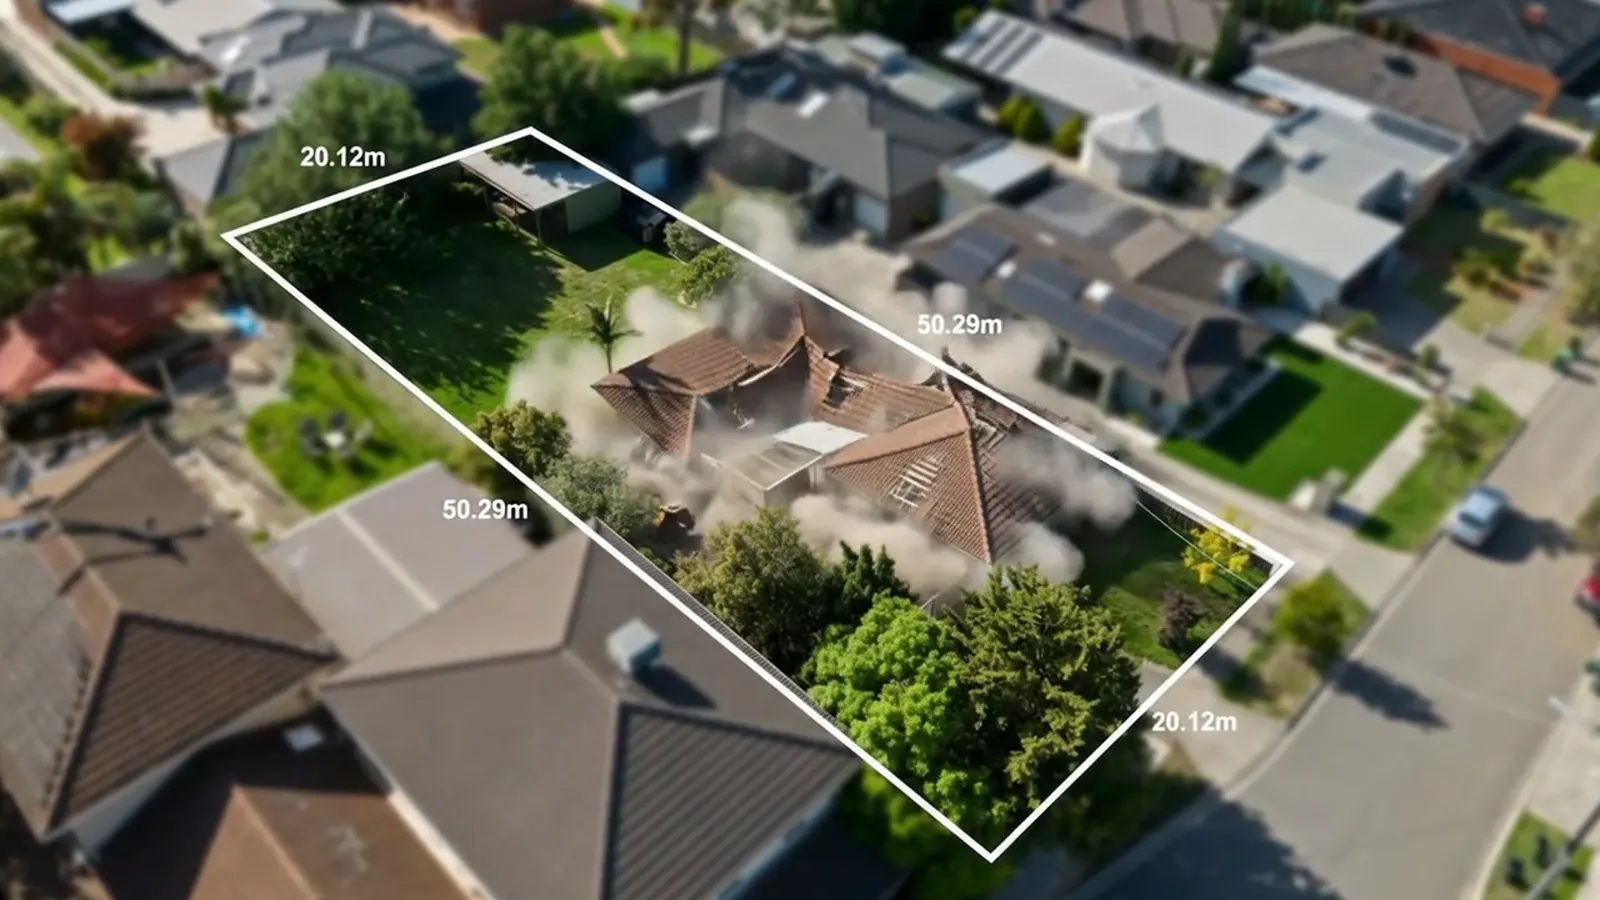
The buy: $807,500 for over 1,000 square metres in the heart of the suburb, with a three bed one bath house already on it. The land alone was valued at $850,000 at the time. So the house was free, and the dirt came in $42,500 under its own valuation.

$807,500
Purchase price
$850,000
Bare land value then
~$900,000
Worth now
4
Townhouses planned

What happened: worth around $900,000 just six months later. That capital is funding stage two: the front house comes down, four townhouses go up, and the lot gets strata titled into a cashflow positive development. The suburb has backed the call too, up 7.8% over the year with vendors now getting 99% of asking price.

Stress tested before we bought: at 2% higher rates, interest on an 80% loan here is $248 a week more. The purchase had to hold at that number first. Every one of ours does.

Bought mid 2026

Victoria

What we saw: an entry point around the mid $600s within a short run of a regional city centre, the deepest sales volume of anything on our list at roughly 500 house sales a year, and a suburb that has run 16.7% in 12 months with vacancy falling from 2.25% to 0.88%. Liquidity like that means you can buy without paying a premium and sell without waiting.

The buy, happening right now: the vendor wanted $650,000. Our inspection flagged problem areas, and the building and pest came back with major defects in the exact bathroom the clients, two builders, were planning to renovate anyway. That report became another $25,000 off, and we secured it at $605,000.

$650,000
Vendor wanted
$605,000
Purchase price
$45,000
Under the ask
~$670,000
Post-reno value

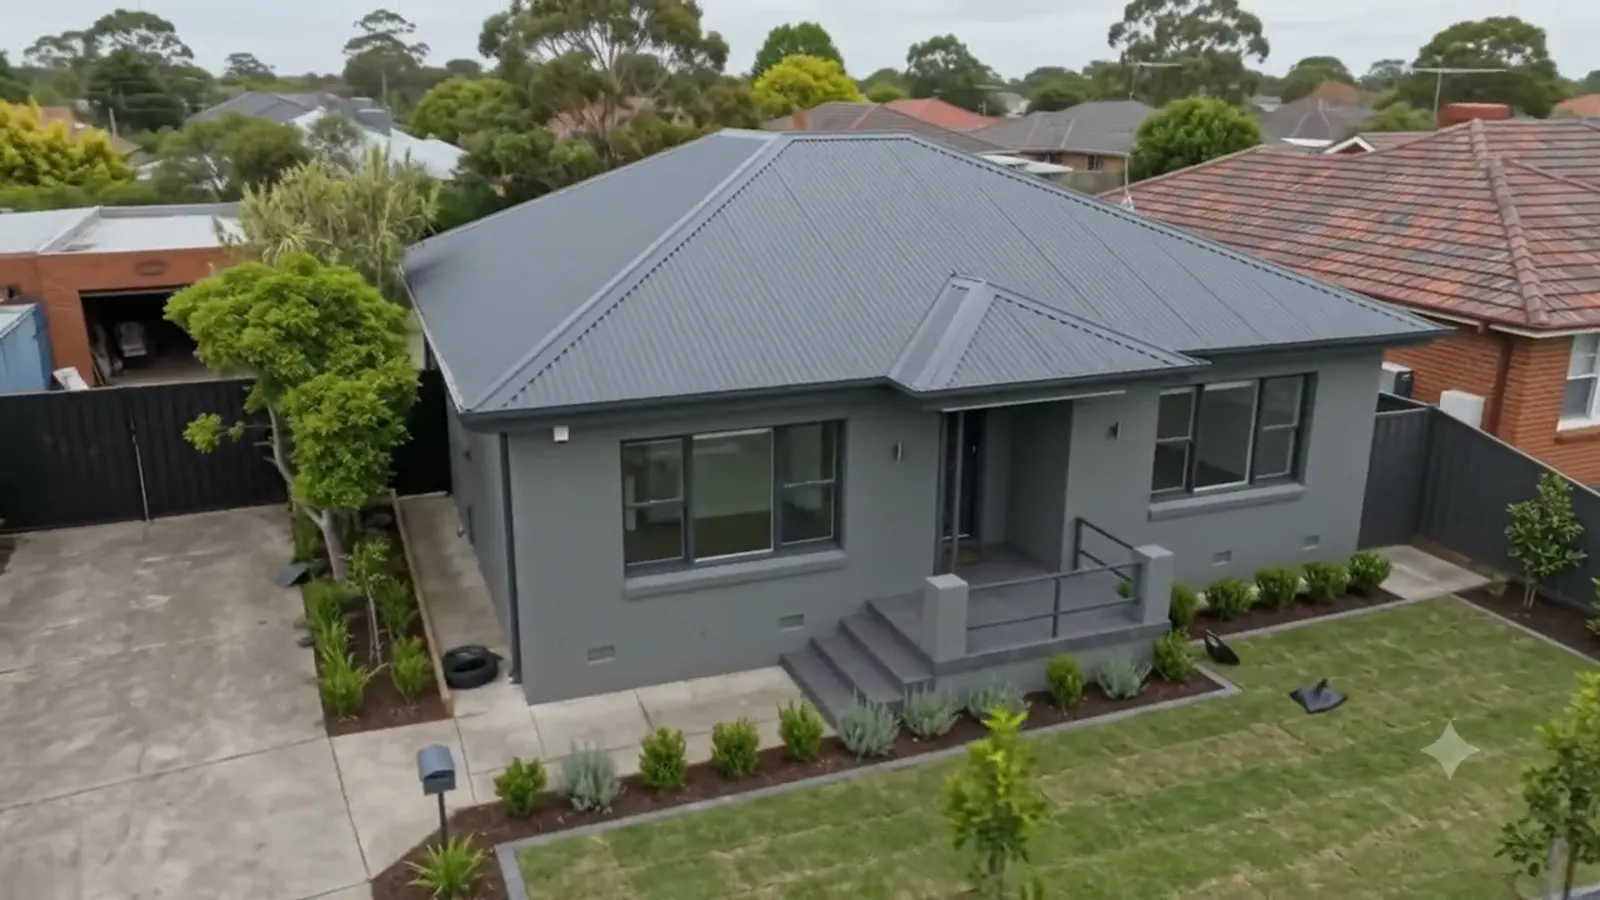
What happens next: the boys have early access to renovate before settlement, so it hits the rental market the day it's theirs, in a suburb with 0.88% vacancy. Once renovated it should be worth around $670,000, and the block has room for a granny flat down the track, a second income sitting in the backyard whenever they want it. Buying a renovator's problem at a discount, with the trades to fix it themselves, in a market still running. That's the brief, matched.

Stress tested before we bought: at 2% higher rates, interest on an 80% loan here is $186 a week more. The purchase had to hold at that number first. Every one of ours does.

Bought May 2026

Victoria

What we saw: a regional service town of 10,000 people with a hospital, a base of wool and agriculture money, and a housing market nobody was watching. Vacancy at 0.55%. A typical three bedder at $428,000 renting for $399 a week. And a modern two bathroom house, the thing tenants ask for first, is rare on the ground there.

The buy: $465,000 for a 2009 built three bed, two bath on 588 square metres. Same-street three bed, two bath stock was selling at $500,000 and over, so this was bought under its own street. The clients' second purchase with us, eight months after their first, and the yield play to sit beside the growth play.

$465,000
Purchase price
$510,000
Valued 6 months later
+$45,000
Growth
5.03%
Gross yield

What happened: leased at $450 a week, a 5.03% gross yield on the purchase price, in a town with vacancy under 1.5%. Six months later the sales on the same street and the next one over, $500,000 and $520,000 for the same configuration, put it at $500,000 to $520,000. Up $45,000 on a $465,000 buy, while paying its own way. That is what the regional end of a portfolio is for.

Stress tested before we bought: at 2% higher rates, interest on an 80% loan here is $143 a week more. The purchase had to hold at that number first. Every one of ours does.

Bought December 2024

Queensland

What we saw: the biggest city in northern Australia with a job base that does not depend on tourists. Health care and public administration, which up here means the army base and the hospital, are the two largest employers, and employed residents were up 8% in five years. Houses had just run 21% in a year off a low base, rents were up from $381 to $494 a week in three years, vacancy was tight, and 4,600 houses a year change hands, so the exit is never a problem.

The buy: $608,000 for a house in an established suburb, bought in December 2024 while most people were still calling the city a mining town.

$608,000
Purchase price
$790,000
Appraised now
+$182,000
Growth
$700/wk
Rents for

What happened: appraised at $790,000 by a local selling agent 22 months later, up $182,000, or 30%. It rents for $700 a week, which is a 6% gross yield on what was paid. Houses across the city did 18% in 2025 and another 9% so far in 2026, and the dial now reads Slowing rather than Peak, so the fast part is behind it. Which is fine. The fast part is the part you got.

Stress tested before we bought: at 2% higher rates, interest on an 80% loan here is $187 a week more. The purchase had to hold at that number first. Every one of ours does.

Bought December 2024

Queensland

What we saw: this city has the cleanest long price record of any regional city we track. Two down years in sixteen, neither worse than 1%, and houses compounding at 7.9% a year for a decade. Health care is the biggest employer, overseas migration is doing the population growth, vacancy sits under 1%, and rents had gone from $457 to $584 a week in three years. A market that rises slowly and never gives it back, and in December 2024 it had not yet started to run.

The buy: $680,000 in December 2024 for a house in one of the suburbs we had shortlisted, the same month as the purchase above, and the first of two buys in this city inside four months.

$680,000
Purchase price
$850,000
Appraised now
+$170,000
Growth
$700/wk
Rents for

What happened: appraised at $850,000 by a local selling agent 22 months later, up $170,000, or 25%. It rents for $700 a week, a 5.4% gross yield on what was paid. Houses across the city did 14.5% in 2025 and 9% so far in 2026, vacancy is 0.83%, and the median rent is now $655. Honest footnote: this city reads Peak on the dial and 25% in under two years is not the long-run rate. The long-run rate is 7.9%, and that is the number it was bought on.

Stress tested before we bought: at 2% higher rates, interest on an 80% loan here is $209 a week more. The purchase had to hold at that number first. Every one of ours does.

Bought March 2025

Queensland

What we saw: the same fundamentals three months after the first purchase, with the price starting to move. Vacancy under 1%, rents still compounding, and a council building fewer than 700 houses a year for 179,000 people. The brief this time was a lower entry, so the search went to the suburbs still trading under $600,000.

The buy: $583,000 in March 2025 for a different client, bought under the $600,000 line while there was still stock under it.

$583,000
Purchase price
$700,000
Appraised now
+$117,000
Growth
$650/wk
Rents for

What happened: appraised at $700,000 by a local selling agent 19 months later, up $117,000, or 20%. It rents for $650 a week, a 5.8% gross yield on the purchase price. Two houses in the same city bought four months apart for two clients, both up around $120,000 to $170,000 and both paying their own way. The lower entry gave up a little growth and took a little more yield, which was the point.

Stress tested before we bought: at 2% higher rates, interest on an 80% loan here is $179 a week more. The purchase had to hold at that number first. Every one of ours does.

Bought June 2025

Victoria

What we saw: the Latrobe Valley had sat flat for two years after its Covid run, down 1% in 2023 and up 2% in 2024, while the jobs kept coming. Employed residents up 12.6% in five years, health care the biggest employer, and the cheapest entry in Victoria for a house with a yard, an hour and a half from Melbourne. Flat prices on a rising job base is the setup. You buy before the market notices.

The buy: $473,000 in June 2025 for a house on the quieter side of a two-town market, bought while the suburb was still priced off the flat years.

$473,000
Purchase price
$560,000
Appraised now
+$87,000
Growth
$500/wk
Rents for

What happened: appraised at $560,000 by a local selling agent 16 months later, up $87,000, or 18%. It rents for $500 a week, a 5.5% gross yield on the purchase price. Latrobe houses did 10% in 2025 and 11% so far in 2026, and the market noticed. Two honest caveats: vacancy is 2.3%, looser than we like, and the council approved 472 houses last year, up from 303, so supply is answering. The Valley is a buy-before-the-run market, and the run has started.

Stress tested before we bought: at 2% higher rates, interest on an 80% loan here is $146 a week more. The purchase had to hold at that number first. Every one of ours does.

Purchase prices and valuations are real client purchases, shared with permission. The third post-renovation figure is an estimate, not a completed valuation. The fourth valuation is our own check-in estimate set off the nearest comparable sales, not a bank valuation. The Queensland and sixth Victorian figures are current appraisals from local selling agents, not bank valuations. Suburb medians and market metrics, houses only, sourced from HTAG: entry figures as at July 2025, current figures as at 30 June 2026 for the first three, and council-level history to 31 August 2026 for the rest. Past growth is not a promise about the next 12 months.

On camera

Two clients, in their own words.

The ticker up top is reported speech, which is doing these blokes a disservice. So here are Sam and Josh saying it themselves. Shot on their own phones, unscripted, and shared with permission. Sound on, or hit CC if you're somewhere you can't.

Sam · BFA client · 3 min 12

Josh · BFA client · 1 min 59

The next opportunity, built around what you need, is waiting.

Every one of these purchases started as a data screen months before anyone walked through a door. Bring your situation, I'll bring the shortlist. If nothing else, you cop 15 minutes of me talking about property and it costs you nothing.

Not ready to talk? Fair enough. The pricing page has the whole fee, in writing, no call required.

Someone else needs convincing?

One page by email: the fee, the five terms, two real purchases, the guarantee. Sent once, to them, nothing else follows.

Find out if I should buy this year